HD Hyundai pivots to gas ships and grids as refining earnings halve
Shipbuilding delivered 1.45 trillion won in operating profit, offsetting a 50.6% drop at oil subsidiary HD Hyundai Oilbank on narrow cracks.
HD Hyundai accelerated its capital shift toward liquefied gas carriers, naval vessels and electrical grid equipment on Nov. 18, 2026, offsetting quarter-on-quarter refining margin contractions at its petroleum subsidiary.
The intermediate holding company HD Korea Shipbuilding & Offshore Engineering generated 1.45 trillion won ($1.08 billion) in third-quarter operating profit. That single maritime division accounted for 49.6% of HD Hyundai's 2.92 trillion won consolidated operating income.
Downstream refiner HD Hyundai Oilbank saw third-quarter operating profit contract 50.6% from the preceding quarter to 900.9 billion won. Narrower refining cracks across regional hubs and inventory valuation shifts caused the sequential drop, the company said.
The group is redirecting capital expenditure away from cyclical refining toward long-cycle industrial contracts. South Korean conglomerates have historically relied on fuel refining to provide stable baseline cash flows during maritime downturns.
That traditional balance has reversed across Asian heavy industrial markets. Environmental shipyard orders and power infrastructure expansions now generate higher operating margins than fossil fuel processing plants, according to group regulatory filings.
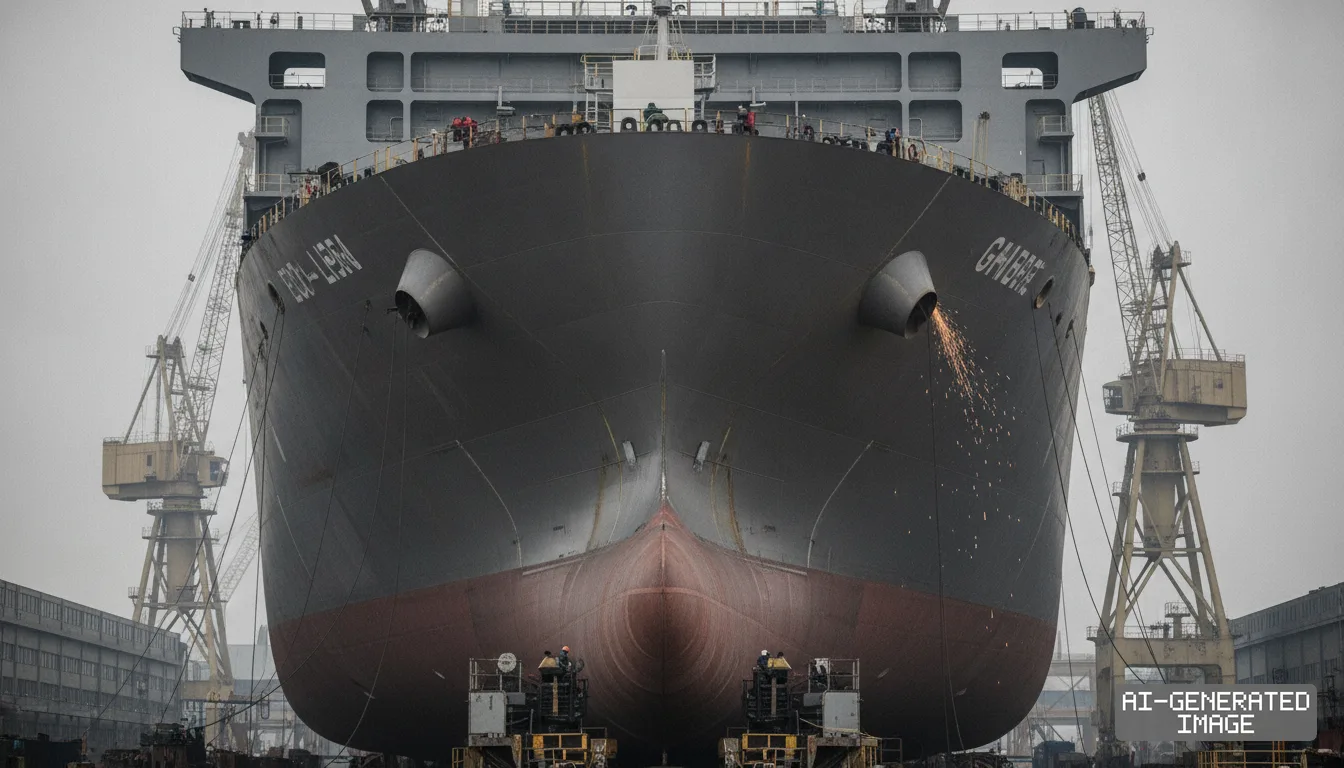
Shipbuilding unit HD Hyundai Heavy Industries led yard performance with operating profit of 899.2 billion won on revenue of 5.75 trillion won. Operating profit at the Ulsan yard jumped 61.3% from a year earlier, the company said.
Higher prices for previously contracted liquefied natural gas (LNG) carriers boosted yard revenues. Premium delivery slots booked during early 2023 entered drydock assembly phases throughout the third quarter, reducing low-margin commercial vessel exposure.
Regional unit HD Hyundai Samho recorded an operating profit margin of 20.2%, generating 479 billion won in operating profit on revenue of 2.37 trillion won. Operating profit at the Mokpo shipyard climbed 56.3% year-over-year.
Dedicated construction of high-capacity gas carriers shielded HD Hyundai Samho from broader industrial wage inflation. The shipyard scheduled consecutive berths for membrane-type cryogenic gas tankers, maximizing series-construction efficiency across its docks, the unit said.
Propulsion manufacturing affiliate HD Hyundai Marine Engine posted an operating margin of 28.5%. The engine unit recorded 60.3 billion won in operating profit, up 197% from the previous year.
Demand for dual-fuel engines — machinery engineered to burn liquefied natural gas alongside conventional diesel fuel — drove the margin expansion. Deliveries of high-specification engines concentrated in the third quarter, the company said in an exchange disclosure.
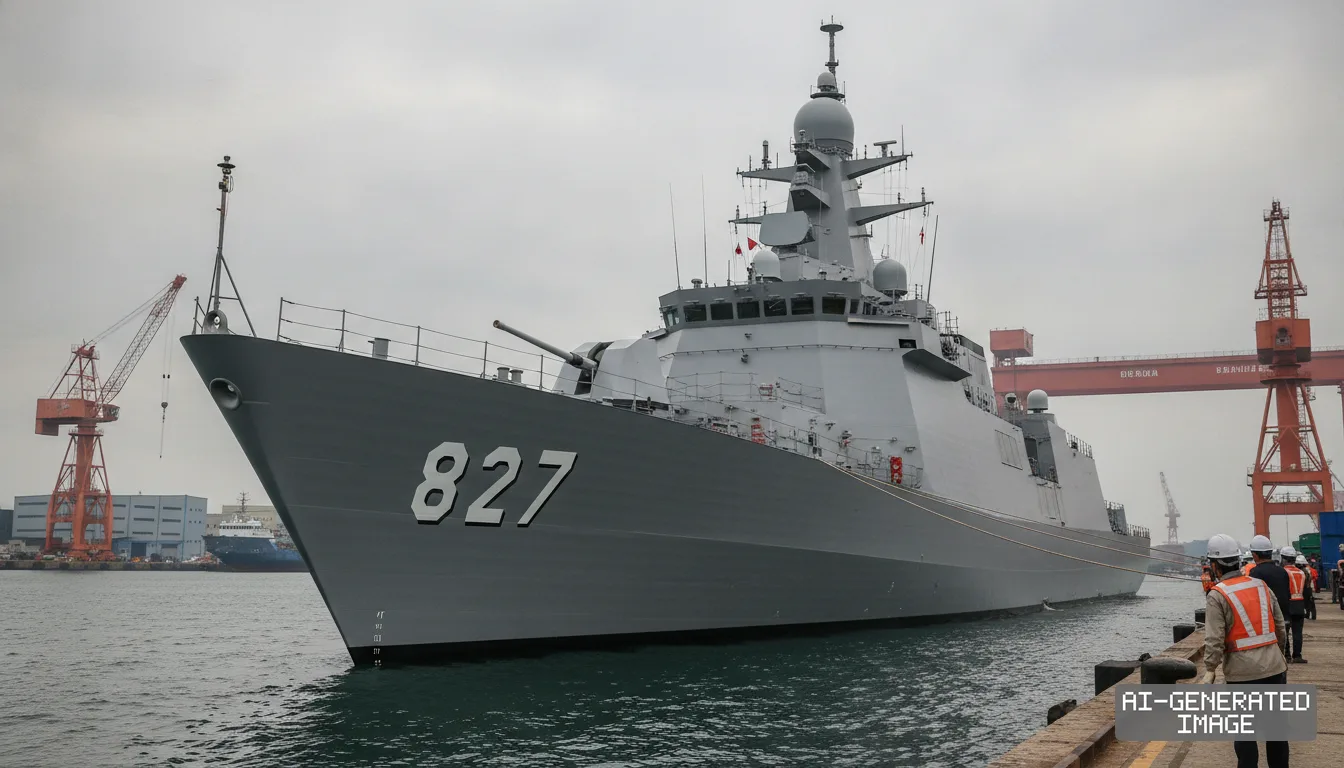
The naval and defense shipbuilding segment represents the next target for multi-year capital deployment. HD Hyundai Heavy Industries plans to expand annual naval and special vessel revenue from roughly 1 trillion won to 10 trillion won by 2035.
Executive Vice President Choi Tae-bok confirmed that naval expansion target during an operational briefing in Ulsan. The naval unit intends to supply surface combatants, auxiliary vessels and export submarines to Indo-Pacific maritime security partners.
Electrical hardware affiliate HD Hyundai Electric reported third-quarter operating profit of 284.5 billion won, rising 15.1% year-over-year. Revenue at the power apparatus division climbed 18.5% to 1.18 trillion won, according to its regulatory filing.
Equipment sales to artificial intelligence data centers and semiconductor fabrication plants fueled the revenue growth. The division's distribution equipment unit posted an 85.8% year-over-year sales increase, supported by American grid expansion projects, the company said.
HD Hyundai Electric accumulated an order backlog of $8.84 billion by the end of September. That order total represents a 26.6% increase compared to the backlog reported twelve months earlier.
Full factory schedules led the electrical affiliate to turn down low-margin inquiries. The company confirmed during an investor call that delivery slots for high-voltage transformers remain booked through late 2028 across Korean production facilities.
To meet regional demand, HD Hyundai Electric committed 198 billion won ($149 million) to expand its Cheongju distribution equipment campus. The 26-month construction project aims to add 250 billion won in annual manufacturing output, the company said.
The electrical expansion counters performance volatility at HD Hyundai Oilbank. The petroleum subsidiary generated 10.04 trillion won in third-quarter revenue, representing 45.5% of total group turnover, but its operating margin contracted to 9.0%.
Chinese chemical supply additions also pressured downstream margins. HD Hyundai Oilbank's petrochemical subsidiary incurred an operating loss of 123.8 billion won as Asian ethylene spreads fell below integrated operational break-even levels.
The corporate reallocation limits group exposure to fluctuating oil import prices. Long-term vessel contracts and fixed-price power equipment orders lock in processing spreads several years ahead of equipment delivery dates, according to company filings.
The group's financial disclosures do not state the exact profit margin breakdown between liquefied gas carriers and container vessels in its remaining order backlog, and management has not published yard slot delivery schedules beyond 2028.
HD Hyundai finalizes commercial terms for new data center distribution equipment contracts on Nov. 30, 2026, setting baseline production volumes for the planned Cheongju plant expansion.
Impact map
How this development propagates across the region and out to global buyers.
| Event | Korea | China | Japan | Global impact |
|---|---|---|---|---|
| HD Hyundai capital reallocation | HD KSOE and HD Hyundai Electric lock in domestic yard and factory capacity through 2028 | Petrochemical overcapacity suppresses margins at Korean refining units like Oilbank | Japanese shipbuilders face wider pricing divergence against high-margin Korean LNG yards | Utilities and AI data center operators absorb premium grid transformer pricing amid tight Asian supply |
In this story
- Companies
- HD HyundaiHD Korea Shipbuilding & Offshore EngineeringHD Hyundai ElectricHD Hyundai Oilbank
- Tickers
- 267250.KS009540.KS267260.KS
- Exposed
- HD Hyundai Heavy IndustriesHD Hyundai SamhoHD Hyundai Marine Engine
- Impact
- CapexOrder BookCost Structure
Related briefings
- HD Hyundai names Lee Sang-kyun head of group shipbuilding units Also on HD Hyundai Marine Engine, HD Hyundai Samho, HD Hyundai
- HD Hyundai Marine Engine inks WinGD pact for dual-fuel units Also on HD Hyundai Marine Engine, HD Hyundai Samho, HD Hyundai Heavy Industries
- HD Hyundai Robotics delivers first one-ton factory robot in Korea Also on HD Hyundai Electric, HD Hyundai Heavy Industries, Order Book
- HD Hyundai Electric holds top US transformer market share at $8.5B Also on HD Hyundai Electric, Order Book
Sources
Primary documents
Reporting
Confidence: high — how we grade this
The documents behind this briefing are linked above. East Asia Brief produces its English text with AI assistance under human editorial review, and does not translate or republish other outlets' articles. See our methodology and AI policy. Spotted an error? Tell us.
The Morning Brief
What changed in Korean, Chinese and Japanese industry overnight — and what it means for your supply chain. One email, weekday mornings, US time. Free.
The Morning Brief is in preparation. Leave your address and we will write to you once — when the first issue is ready. Nothing before that.